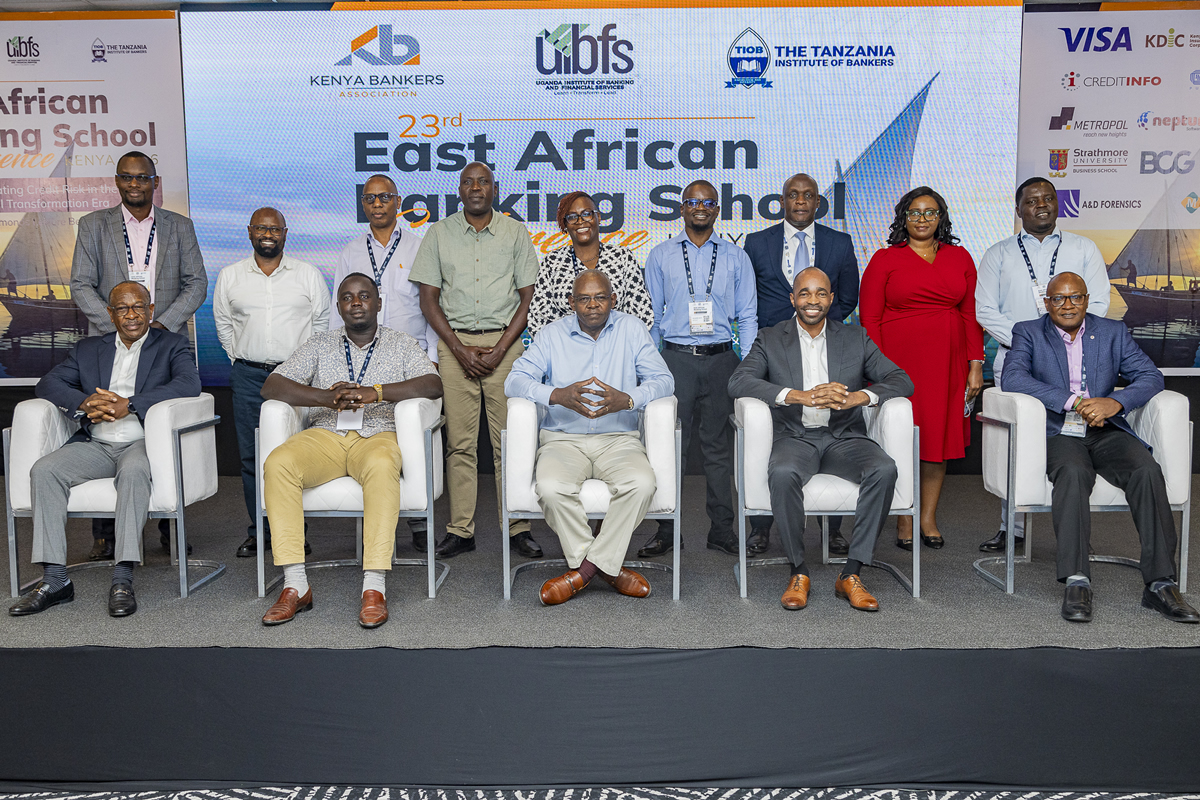
Diani, Kenya, July 14, 2026…Banks across East Africa have been urged to rethink traditional lending models by reducing their reliance on collateral and embracing artificial intelligence (AI), alternative data and advanced analytics to responsibly expand access to credit for individuals, entrepreneurs and small businesses.
The call was made during the 23rd East African Banking School (EABS) Conference held in Diani, Kwale County, where regulators, policymakers, banking leaders, technology providers and development partners explored how digital transformation is reshaping credit risk management while advancing financial inclusion across the region.
The conference was organised by the Kenya Bankers Association Institute (KBAI) in partnership with the Uganda Institute of Banking and Financial Services (UIBFS) and the Tanzania Institute of Bankers (TIOB), with the support of Platinum Partners Visa, the Kenya Deposit Insurance Corporation (KDIC) and KCB Group. Other partners included Spin Mobile, Neptune Software Group, Boston Consulting Group, Credit Information Sharing Association of Kenya (CIS Kenya), Strathmore University, TransUnion, Prime Bank, and Metropol CRB.
The conference highlighted the growing need for financial institutions to modernise credit risk management as customer behaviour becomes increasingly digital and data-driven. Delegates agreed that leveraging artificial intelligence, alternative data and predictive analytics can enable banks to make faster, more informed lending decisions while responsibly extending credit to underserved individuals and businesses.
Opening the conference, Central Bank of Kenya Governor Dr. Kamau Thugge said Kenya had made encouraging progress in expanding private sector credit, with growth reaching 9.3 per cent by the end of May, but noted that further expansion was necessary to support economic growth.
“I do believe that we need to expand credit to the private sector in double digits, and I think it’s possible and would not be inflationary,” said Dr. Thugge.
The Governor noted that emerging technologies are fundamentally changing how banks originate, assess and manage credit, revealing that nearly 45 per cent of Kenya’s commercial banks already use artificial intelligence in credit risk assessment, according to the Central Bank of Kenya’s 2025 Innovation Survey.
He, however, cautioned that technology must always be deployed within strong governance frameworks.
“AI models should be transparent, explainable and subject to effective human oversight, and ultimately the responsibility for credit decisions must continue to rest with banks and not algorithms,” he said.
Kenya Bankers Association Chairman and KCB Group Chief Executive Officer Paul Russo said the banking industry must move beyond viewing credit risk purely as a defensive function and instead embrace innovation as a driver of sustainable growth and financial inclusion.
“Our ambition should be to explore how innovation, technology, artificial intelligence, alternative data and collaboration can help us better understand risk, reduce it and ultimately make more individuals, businesses and communities bankable,” Russo said.
He noted that while collateral will continue to play an important role in lending, it should no longer serve as the primary determinant of creditworthiness.
“At the end of the day, our role as banks is not merely to manage risk; it is to responsibly unlock opportunity. Our success should be measured not only by the risks we avoid, but also by the opportunities we create through sustainable access to finance,” he added.
Visa East Africa General Manager Chad Pollock said East Africa’s credit market had reached a pivotal moment, with competition increasingly being determined by institutions’ ability to transform customer data into better lending decisions.
Drawing on Visa Consulting & Analytics research, he noted that Kenya’s lending ecosystem comprises approximately 18 million formal credit users, creating significant opportunities for financial institutions to modernise underwriting models and enhance customer experiences.
Pollock identified three priorities that will define the future of credit risk management: expanding the use of customer and behavioural data, investing in advanced analytics and machine learning, and accelerating real-time credit decision-making.
“The institutions that adapt will thrive. Those that do not risk becoming less relevant to the customers they serve,” he said.
Kenya Deposit Insurance Corporation Chief Executive Officer Mrs. Hellan Chepkwony said digital transformation presents enormous opportunities for improving credit risk management, but stressed that technological innovation must be supported by sound governance and prudent institutional leadership.
“Digital tools can certainly strengthen decision-making, but they cannot replace sound governance, prudent lending practices and strong institutional leadership,” she said.
Mrs. Chepkwony added that partnerships among banks, regulators and financial safety-net institutions remain critical to preserving depositor confidence and strengthening financial stability across the region.
National Assembly Finance and National Planning Committee Chairperson Hon. Kuria Kimani challenged banks to rethink collateral-based lending models, warning that millions of young entrepreneurs remain excluded from formal finance despite having viable businesses.
“Your banks, your institutions are still using collateral as the main basis of lending. If you continue like this, you will have no one to lend to. These young people do not have the collateral you seek. You must up your game in data analytics and risk profiling,” he said.
Throughout the conference, delegates explored how artificial intelligence, machine learning, mobile money transaction histories, digital payment data and other alternative data sources are helping financial institutions improve credit assessment, detect fraud, strengthen portfolio management and responsibly expand lending to previously underserved customers.
Closing the conference, Kenya Bankers Association Chief Executive Officer Raimond Molenje called for greater regional collaboration to position East Africa as a globally competitive financial services hub.
“East Africa has enormous potential, but we must work together to unlock it. We have to collaborate, strengthen regional partnerships and look beyond our national boundaries if we are to build a more competitive and resilient banking sector. Together, we can create a stronger regional financial ecosystem that expands opportunity for our people and businesses,” Molenje said.
The conference brought together banking leaders, regulators, policymakers, technology partners and financial sector practitioners from Kenya, Uganda, Tanzania, Rwanda, Somalia and Burundi, reaffirming the region’s commitment to strengthening credit risk management through innovation, responsible use of technology and closer regional collaboration.
Christine Onyango
Director, Communication and Public Affairs
Kenya Bankers Association
Email: conyango@kba.co.ke
About Kenya Bankers Association
The Kenya Bankers Association (KBA) is the umbrella body for all commercial banks in Kenya and is regulated by the Central Bank of Kenya (CBK). Established on 16th July 1962, KBA represents 46 member institutions with combined assets exceeding KES 7.7 trillion. Its core mandate is to promote a stable, competitive, and inclusive banking industry by influencing legislation, regulation, and policy to enhance access to affordable credit for individuals, households, and businesses. KBA also drives financial sector development through strategic initiatives, including the launch of Pesalink, the industry’s first peer-to-peer digital payments platform. In partnership with the CBK and other stakeholders, KBA has spearheaded projects such as the modernization of the National Payments System, implementation of the Real Time Gross Settlement System (RTGS), and the Kenya Credit Information Sharing Initiative. Guided by its brand statement, “One Industry. Transforming Kenya,” KBA continues to strengthen the banking sector, foster innovation, drive financial inclusion, and support national economic growth. Learn more: www.kba.co.ke